

Catastrophe bond funds structured as UCITS investment strategies are now averaging a 6.67% return for the year to September 25th 2026, which is already the fourth best year on record for the Plenum CAT Bond UCITS Fund Indices.
Specialist catastrophe bond and insurance bond investment manager Plenum Investment’s Index has a history back to 2011 and this year is now on-track to be at the least the fourth best annual return for UCITS cat bond funds.
This despite catastrophe bond returns having declined from their recent historical highs, as reinsurance pricing has softened. The Index shows that returns remain very attractive, with a 6.67% average cat bond fund return year-to-date being a level that compares well with benchmarks and other hedge fund categories, of course with meaningfully less correlation to broader financial markets.
The latest data from the Plenum Index is for the period August 28th through September 25th 2026, for which time-frame the average return of the UCITS catastrophe bond funds reached 1.23%.
It’s again not quite a full month, but this Index data is reported based on Friday’s secondary cat bond marks.
September saw catastrophe bond funds continuing to benefit from positive premium accrual, while there were no impactful natural catastrophe events.
Through 2026 so far, for the closest reported figures to calendar months, UCITS cat bond funds have returned: 0.53% for January; 0.46% for February; 0.35% for March; 0.55% for April; 0.36% for May; 0.62% for June to the 26th of the month; 1.15% for the subsequent period to July 31st; 1.24% on average to August 28th; and now 1.23% to September 25th.
With another strong month of returns, the average year-to-date performance of the UCITS catastrophe bond fund strategies rose from 5.38% as of August 28th 2026, to now 6.67% as of September 25th’s data.
You can analyse the Plenum CAT Bond UCITS Fund Indices in our charts:
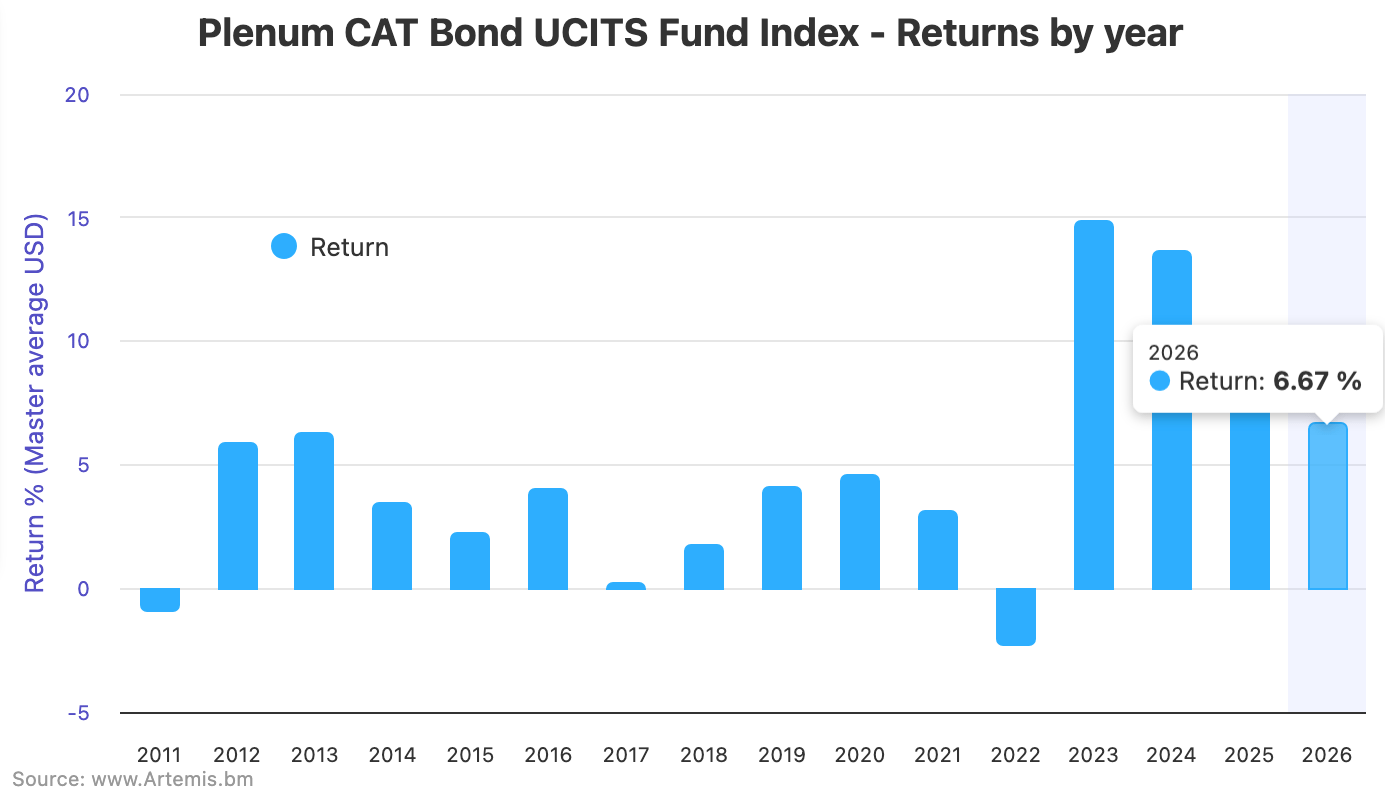
With a 6.67% average return year-to-date, the catastrophe bond sector is already tracking for one of its best performing years on record.
2026 is already the fourth best annual return for this UCITS cat bond fund Index, only now standing behind the last three years in the index-history that began with 2011.
However, it’s important to highlight that the future returns may not live up to the past, while the reinsurance market remains in a softening state.
This is evident in the rolling twelve month return of this catastrophe bond fund index, which at September 25th had declined slightly to 9.66%, down on the August 28th figure of 9.82%.
That rolling twelve month return has been waning over the last few months, affected by the newer cat bond issuance coming to market with soft reinsurance market pricing levels, as older vintage deals mature with higher coupons as well.
However, historically annualised returns in the 9% range is still extremely attractive for the catastrophe bond sector and as we often highlight the attachment terms remain largely stable in the market, although we are seeing the average expected loss across cat bond issuances creeping higher in recent months prior to the summer lull.
Through this latest reporting period of record, from August 28th to September 25th 2026, while the average return of all the UCITS catastrophe bond funds reached 1.23%, the lower-risk cohort averaged almost 1.22% and the higher-risk group of cat bond funds averaged 1.25%, so with little between the groupings.
On a capital-weighted basis the index return was 1.34% for the same period, the best month for this measurement year-to-date in 2026.
On a year-to-date basis to September 25th, the average performance across the cat bond fund Index of 6.67% compares to the lower-risk UCITS cat bond funds now averaging 6.51%, while the higher-risk funds average 6.77% as of August 28th and the capital weighted Index stands at 6.89%.
As we said, the rolling twelve month return of the average UCITS cat bond fund has declined slightly to 9.66%, while for the lower-risk cat bond funds in this Index it declined to 9.52%, but for the higher-risk funds it dropped below double-digits for the first time to 9.69% and on a capital weighted basis it also fell below the 10% mark and currently stands at 9.79%.
As we explained, that 12-month return is declining over recent months, but still remains at a historically attractive level for catastrophe bond investors.
The closest comparable 12-month period of the prior year saw the average rolling-twelve month return of UCITS catastrophe bonds funds standing at 10.91%.
In fact, the gap between the current 12-month rolling-return and the prior period has narrowed slightly in the last month, given the strong performance of cat bond funds through the last four weeks.
Analyse UCITS cat bond fund performance, using the Plenum CAT Bond UCITS Fund Indices.
Analyse UCITS catastrophe bond fund assets under management using our charts here.
Analyse catastrophe bond market yields over time using this chart.
 View all of our Artemis Live video interviews and subscribe to our podcast.
All of our Artemis Live insurance-linked securities (ILS), catastrophe bonds and reinsurance video content and video interviews can be accessed online.
Our Artemis Live podcast can be subscribed to using the typical podcast services providers, including Apple, Google, Spotify and more.