

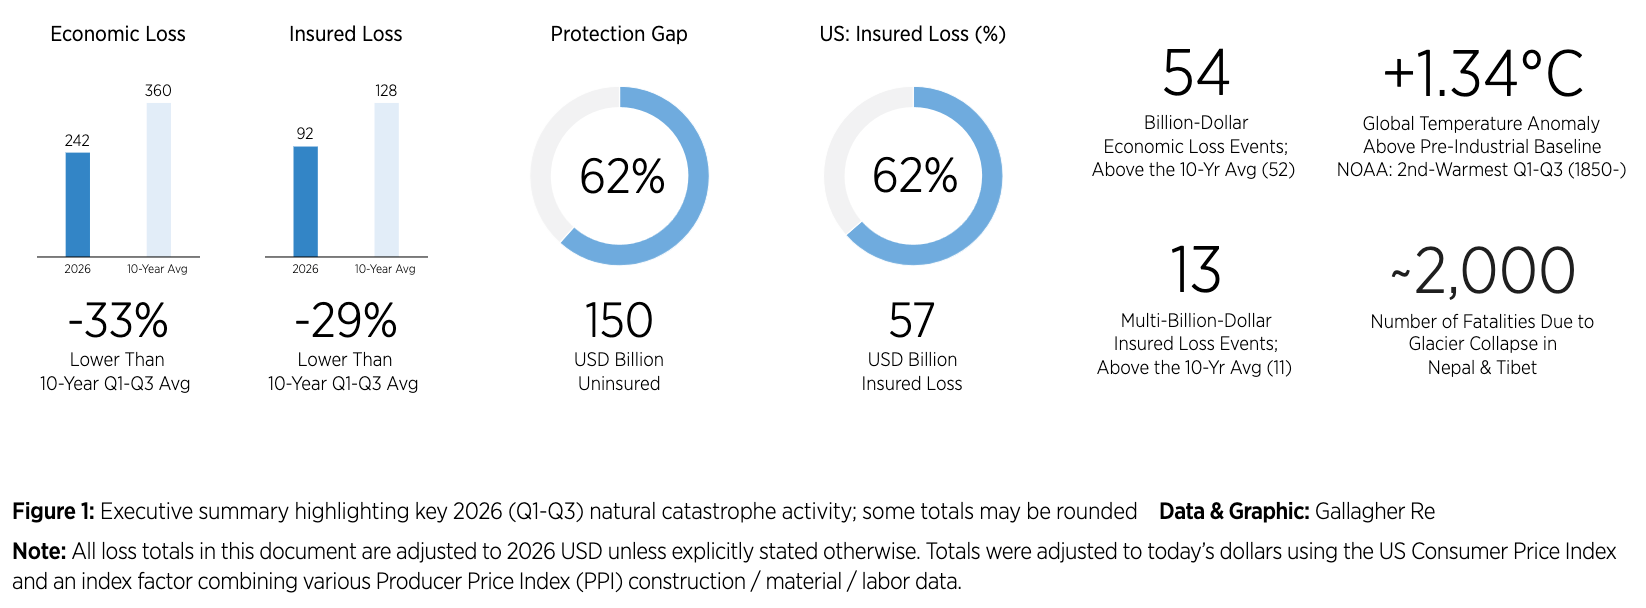
Insured losses from natural catastrophe events across the globe during the first nine months of 2026 are estimated to have reached US $92 billion, representing the lowest total for the first nine months of a year since 2019, and 29% below the 10-year average of $128 billion, according to reinsurance broker Gallagher Re’s Q3 2026 Natural Catastrophe and Climate Report.
 At the same time, the broker noted that severe convective storms (SCS) generated at least $43 billion in insured losses in the United States alone during Q3 2026, while on a global basis, SCS accounted for nearly 60% of all insured catastrophe losses during the first three-quarters of the year.
“The insurance industry has now experienced six consecutive quarters without a single natural catastrophe event generating more than USD10 billion in insured losses, representing one of the longest such stretches in decades,” Gallagher Re said.
“Despite 54 billion-dollar economic loss events and 24 billion-dollar insured loss events globally, both broadly in line with historical averages, lower event severity has kept aggregate losses well below average,” the broker continued.
The image below, taken from Gallagher Re’s latest report, highlights how 2026 continues to run below the 10-year average for both insured and economic losses, while the United States contributes 62% of global insured losses to-date in 2026.
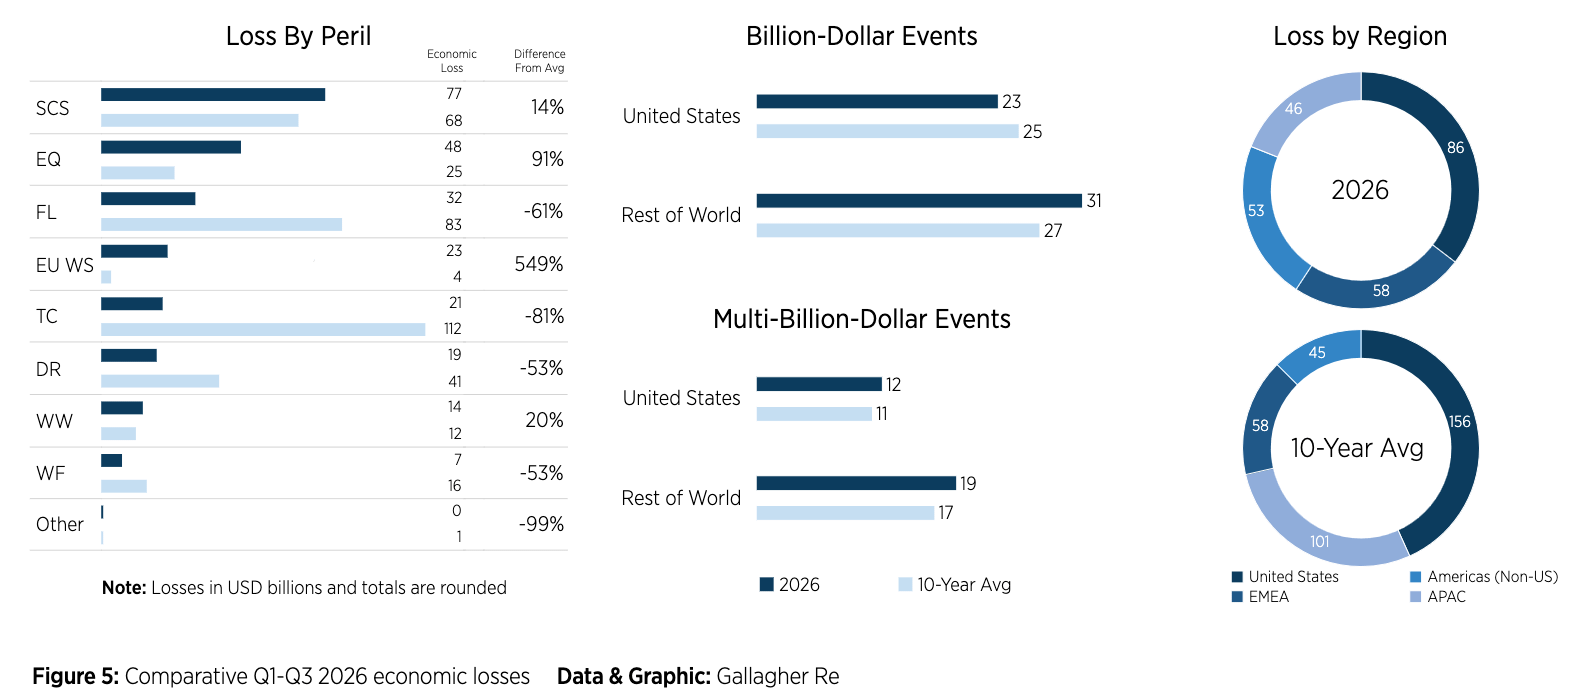
As mentioned, while catastrophe losses have remained subdued, severe convective storms (SCS) continued to dominate industry losses across the globe.
According to Gallagher Re, in the US alone, insurers incurred at least $43 billion in SCS losses through Q3’26, marking a record fourth consecutive year in which annual insured losses from the peril have exceeded $40 billion.
At the same time, Europe has also witnessed heavy SCS activity in recent months, recording at least $9 billion in SCS insured losses, including a $3.8 billion in losses from a late-August outbreak alone.
Severe convective storms also accounted for nearly 60% of all insured catastrophe losses during the first three quarters of the year.
Another image below taken from the broker’s report, showcases that a number of perils such as SCS are running above the ten-year average for insured losses so far in 2026.
Gallagher Re also observed that hurricane activity also contributed to regional losses during the period.
In the eastern Pacific, Hurricanes Lala, Lowell and Nolo all affected the Hawaiian Islands during the third quarter of 2026. Gallagher Re stated that Hurricane Lala was particularly impactful, noting that it passed close to the Big Island in mid-August and became Hawaii’s second weather-related disaster of the year to generate economic losses exceeding $1 billion.
Meanwhile, in the Atlantic, Hurricane Isaias became the first major hurricane of the 2026 Atlantic season before reaching Florida’s Panhandle on October 9th as a Category 2 storm. Gallagher Re importantly noted that because the hurricane occurred outside the nine-month reporting period, its losses were excluded from the broker’s $92 billion nine-month loss total.
However, the broker has said that it expects the storm to generate insured losses in the low to mid-single-digit billions of US dollars.
Despite the relatively low period of below average catastrophe losses recorded so far in 2026, Gallagher Re warned that this should not be interpreted as evidence of reduced underlying risk.
“Alongside elevated secondary peril activity, 2026 has also been marked by the rapid emergence of what could become one of the strongest El Niño events on record,” the broker explained.
“The US National Oceanic and Atmospheric Administration (NOAA) projects a greater than 81% probability that El Niño will maintain a “very strong” status into January 2027. Forecasts suggest the event could peak during the fourth quarter before weakening during 2027, with the potential for a subsequent transition to La Niña conditions. For (re)insurers, such shifts can materially alter regional risk patterns, creating the need to reassess exposure concentrations, accumulations and capital deployment strategies,” Gallagher Re added.
Gallagher Re’s report also highlighted historical evidence linking ENSO transition periods with meaningful changes in catastrophe activity. The broker said monitoring these developments would be important as the industry beings to prepare for the 2027 renewal season.
Rising temperatures and prolonged drought were also identified as major themes of 2026. Gallagher Re stated that global temperatures during the first nine months of 2026 ranked as the second highest recorded for that period in the modern historical record, which extends back to at least 1850.
Multiple countries, including France, the UK and the contiguous United States experienced their warmest summers on record for the June-to-August period. The resulting consequences included increased wildfire activity, agricultural losses, disruption to transport networks and a substantial rise in insurance claims linked to drought, particularly in France.
Steve Bowen, Chief Science Officer at Gallagher Re, commented: “At first glance, 2026 appears to have been a relatively favorable year for the insurance industry. Global insured losses have remained below recent averages, largely because the industry has avoided a meaningful concentration of major loss events. We have now gone six consecutive quarters without a natural catastrophe generating more than USD10 billion in insured losses, an unusually long stretch by historical standards.”
Bowen continued: “However, catastrophe activity and catastrophe losses are not necessarily the same thing. The world has still experienced a sizeable number of significant disasters in 2026, but relatively few have occurred in locations or under circumstances that generated outsized insured losses. Many of the costliest events instead produced substantial economic, humanitarian, and societal impacts, with much of the recovery ultimately falling on governments, businesses, and affected communities.
“Looking ahead, the potential transition toward La Niña conditions in 2027 is a reminder of how quickly the catastrophe landscape can shift from one year to the next. Periods like this provide an opportunity to reassess exposures, accumulations, and portfolio resilience. History tells us that more active and costlier periods can return, and organizations that use quieter years to prepare are often best positioned when conditions do eventually shift.”
 View all of our Artemis Live video interviews and subscribe to our podcast.
All of our Artemis Live insurance-linked securities (ILS), catastrophe bonds and reinsurance video content and video interviews can be accessed online.
Our Artemis Live podcast can be subscribed to using the typical podcast services providers, including Apple, Google, Spotify and more.