

Through the recent period of brisk issuance the catastrophe bond market has been expanding rapidly, with now 20% more cat bond deals available to investors than a year ago, analysis from specialist Swiss insurance-linked securities investment manager Euler ILS Partners shows.
 In its review of the market after the third-quarter of 2026, Euler ILS Partners found that the size of the market had increased 17.3% year-on-year, while the number of deals outstanding rose slightly faster by 20% to reach 402.
This expansion in market breadth means more individual investment opportunities are available to cat bond fund managers and investors, which helps in portfolio construction and diversification.
But the metrics speak to a softening marketplace, with the average coupon of the cat bond market down 9.2% at 7.14% and the average spread down faster with a 21.6% decline YoY to 5.05%.
The market has seen its issuance increasingly concentrated in the 1% to 3% expected loss range, Euler ILS Partners noted, which has raised the average expected loss of outstanding catastrophe bonds by 12.5% YoY to 2.4%.
Euler ILS Partners’ data previously showed the average expected loss of the cat bond market had risen from 2.29% at the end of Q1 2026 to 2.31% by the end of the second-quarter, so the increase has continued.
Euler ILS Partners commented as to how the market’s expected loss has developed, saying, “The share of issuance in the 1% to 3% expected-loss range increased from 37% in 2018 to 64% in 2026 YTD. As a result, lower-EL layers have become less prevalent in new issuance.”
You can see how expected losses of catastrophe bond issuance have developed by year in the chart below, which shows the weighted average across 2026 issuance so far at 2.67%.
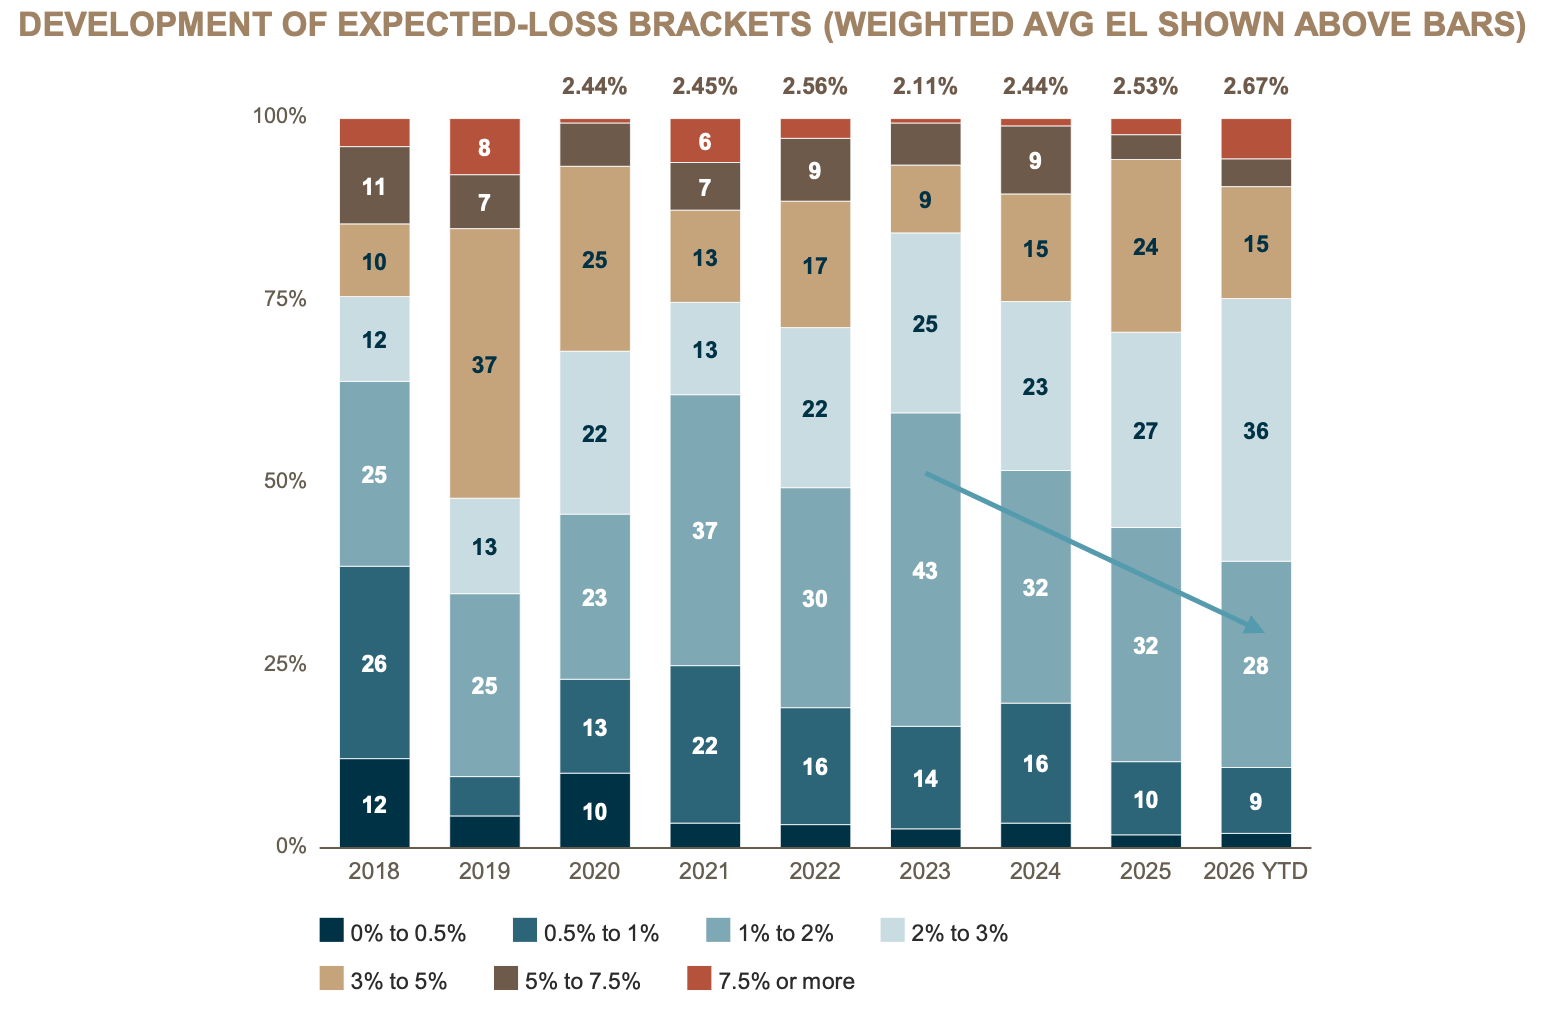
Euler ILS Partners chart (above) shows issuance contracting fastest in the 1% to 2% EL range and increasing in the 2% to 3% range, which suggests the weighted average may increase further as this year progresses.
Through reinsurance market cycles the average expected loss of cat bond issuance tends to rise when prices soften, as sponsors capitalise on being able to bring higher-risk deals to market.
At the same time, through the third-quarter of 2026 the composition of perils in the cat bond market remained relatively stable according to Euler ILS Partners’ data.
US hurricane risk still accounts for around 75% of exposure after Q3, so flat with the end of Q2 figure, but up from 74% as of the end of Q1.
Euler ILS Partners said, “Cat Bond market composition remained broadly stable, with US hurricane risk represented in approximately 75% of exposure. US earthquake risk remained the next-largest individual segment.”
 View all of our Artemis Live video interviews and subscribe to our podcast.
All of our Artemis Live insurance-linked securities (ILS), catastrophe bonds and reinsurance video content and video interviews can be accessed online.
Our Artemis Live podcast can be subscribed to using the typical podcast services providers, including Apple, Google, Spotify and more.